Where you keep physical gold changes more than security. It affects insurance, legal records, access, annual cost and how easily you can sell. A home safe, bank safe-deposit box and specialist private vault each solve some problems while creating others. The best choice is the one you can document and manage, not the one with the strongest marketing claim.
A home safe offers direct possession but makes security and insurance your responsibility. A bank box separates metal from home but can restrict access and may not insure contents. A private vault can add professional custody, records and buyback, but charges fees and introduces provider dependencies. Verify insurance and sale terms in writing.
Home safe: maximum possession, maximum personal responsibility
Keeping gold at home gives immediate physical access without a storage provider’s opening hours or approval. It also makes you responsible for burglary resistance, fire and water protection, discreet delivery, insurance, records and a safe way to transport metal for resale. A small locked box is not automatically a suitable bullion safe, and hiding an item does not establish insurance coverage.
Speak to the insurer before the metal arrives. Ask whether bullion is covered, the single-item and total limits, required safe specification, installation standards, valuation method and exclusions. Obtain the answer in writing. Recheck coverage when the holding or gold value increases. Store invoices and photographs securely away from the safe, and limit who knows about the holding.
Avoid publishing your address, storage location, serial numbers or delivery routine. Plan how an executor or trusted person would access the property without sharing access details more widely than necessary. Home storage can reduce dependence on a custodian, but it does not remove risk, it transfers operational work to you.
Bank safe-deposit box: physical separation without assumed insurance
A safe-deposit box moves valuables away from home and into a controlled facility, but the rental agreement determines access and responsibility. Banks may require notice, identification, branch opening hours and advance payment. You may be unable to retrieve contents at the exact moment you want them, and bank deposit protection should not be assumed to cover physical box contents.
Insurance is the crucial check. Lloyds states that it does not provide insurance cover for items stored in its safe-deposit boxes; UBL UK tells customers that insuring box items is their responsibility. Other providers can have different terms, so read the actual agreement and arrange appropriate cover rather than treating the bank vault as an insurance policy.
- Ask whether bullion is permitted and whether any value or product limits apply.
- Confirm access hours, notice, joint-holder rights, missed-payment rules and lost-key charges.
- Establish who insures theft, damage and unexplained loss, and under what exclusions.
- Do not assume FSCS deposit protection treats physical valuables like an eligible cash deposit.
- Keep an independent inventory, proof of ownership and an estate-access plan.
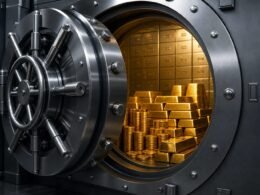
Private vault: professional custody with contractual dependencies
A specialist private vault can offer controlled access, insurance, bar lists, reconciliation and integrated buyback or delivery. These features are useful for long-term holdings and for owners who do not want the personal security burden. They also introduce recurring charges and reliance on the platform, vault operator, insurer and banking route.
Ask whether your holding is allocated, dedicated, segregated, mutualised or unallocated. Confirm who legally owns the metal, which entities provide custody and insurance, how independent audits work and what happens if the platform fails. ‘Outside the banking system’ does not mean outside all legal, operational or payment systems. Professional storage is a structure to evaluate, not a magic label.
Side-by-side comparison
| Criterion | Home safe | Bank safe-deposit box | Private precious-metals vault |
|---|---|---|---|
| Physical access | Immediate under your control | Branch hours, notice and rental terms | Appointment, provider process or delivery |
| Insurance | Your policy; limits and exclusions need written confirmation | Often your responsibility; check rental terms | May be included; verify insurer, scope and valuation |
| Ownership evidence | Invoices, photographs and personal inventory | Personal inventory plus box agreement | Certificates, bar lists and reconciliations where offered |
| Recurring cost | Possible insurance and maintenance | Box rental and separate insurance | Percentage and/or fixed storage/account fees |
| Main dependency | Your security and insurance setup | Bank access and contract | Platform, vault, insurer and bank settlement |
| Sale logistics | Transport to dealer or arranged collection | Retrieve then transport or arrange collection | Integrated buyback may be available; compare net price |
Compare the real annual cost
Home storage may appear free because there is no vault invoice, but a suitable safe, installation and insurance can cost money. A bank box has rental and insurance considerations. A private vault can charge a percentage of value plus fixed account fees. Compare all three over your intended holding period, including the time and transport required to sell.
For a vaulted account, divide total annual storage and fixed fees by your holding value. A $100 fixed fee adds 2% to a $5,000 balance before percentage storage. For home or bank storage, include the incremental insurance premium and any required security expenditure. Do not count general home costs that you would pay anyway as if they were caused solely by gold; identify the additional cost.
Access during an emergency
Decide what ‘emergency access’ means. If you may need cash quickly, physical gold at any location is not a substitute for an emergency fund. If you want the option to collect metal personally, home storage offers the most direct possession, while bank and private facilities have procedures. If you want to sell without transport, a vault platform with a clear buyback service may be operationally simpler.
Test the process before it becomes urgent. Read how identity checks, bank changes, key loss, account closure, death and incapacity are handled. Keep emergency contact details current. Do not improvise by sharing passwords or unsafe access instructions; use the provider’s authorised process and appropriate legal arrangements.
Insurance and audit evidence to request
| Document | What it should clarify |
|---|---|
| Insurance schedule or summary | Insurer, covered events, exclusions, limits, valuation and claims process |
| Custody/storage agreement | Legal title, custodian, permitted use, fees, termination and liability |
| Bar list or certificate | Owner, location, product, weight, fineness and identifiers where applicable |
| Reconciliation/audit report | Preparer, independence, date, scope, exceptions and customer-total comparison |
| Buyback/delivery terms | Pricing, commission, formats, minimums, timing, transport, tax and bank costs |
A logo or one-line assurance is not enough. Save the documents relevant to your holding and check for updates. For home or bank storage, create your own dated inventory and periodically reconcile it with physical items under safe conditions.
Does splitting storage reduce risk?
Using more than one location can reduce the chance that a single burglary, access restriction or provider failure affects the entire holding. It can also preserve a small amount of direct possession while professional storage handles the rest. The trade-off is more cost, records, access procedures and points of human error.
Splitting is not automatically safer. Two poorly understood arrangements can be worse than one well-documented one. Choose locations for specific reasons, maintain a secure consolidated record and avoid discussing the distribution publicly. The correct number of locations depends on value, purpose and your ability to administer them.
How to move gold between storage locations safely
Moving metal is a separate risk event, not a routine administrative detail. Start by asking both facilities whether they permit the transfer, which products they accept and who can arrange insured specialist transport. Do not post bullion through an ordinary delivery service without confirming in writing that the service and insurance explicitly cover the items and their full value.
- Create a dated inventory listing product, quantity, weight, fineness and serial numbers where applicable.
- Obtain written collection, handover and delivery instructions from the sending and receiving parties.
- Confirm who bears risk at each stage, the insurance limit, exclusions and claims process.
- Reconcile identity and authority so only approved people can release or receive the metal.
- Check customs, declarations, VAT or other tax requirements before any cross-border movement.
- At destination, reconcile the received items against the inventory and obtain updated ownership and storage records.
Keep the transfer documents with your acquisition and storage records. If items are substituted, pooled or re-registered, establish exactly what you own after arrival rather than assuming the original certificate still describes the holding. Never publish transit dates, routes or storage addresses. For a high-value or international transfer, use appropriately qualified professional advice and a documented chain of custody.
A practical decision framework
- Define the holding and its purpose. Do not start with a provider advertisement.
- Decide whether immediate possession, integrated sale, professional custody or the lowest recurring cost matters most.
- Get written insurance answers for each option; reject any assumption that physical security equals financial cover.
- Calculate setup, annual and exit costs over the intended holding period.
- Verify ownership, audit and access documents for off-site storage.
- Plan estate access and a realistic sale route.
- Review the arrangement annually and whenever the holding’s value or your circumstances materially change.
Frequently asked questions
Is a home safe enough for gold bullion?
It depends on the safe, installation, value, location, insurance and your personal security. Ask the insurer what specification is required and whether bullion is covered. A fire-resistant document box may not provide the burglary protection or policy compliance needed for valuable metal.
Are bank safe-deposit boxes insured?
Do not assume so. Some UK banks explicitly state that insurance is the customer’s responsibility or that they do not provide cover. Read the rental agreement and arrange your own suitable policy where necessary. Physical box contents are not the same as an eligible cash bank deposit.
Is private vault storage always allocated?
No. A professional facility can hold allocated, pooled, dedicated or unallocated arrangements depending on the provider and contract. Ask what you legally own and what evidence you receive. The building’s security does not define your property rights.
What is the cheapest way to store gold?
There is no universal cheapest option after risk is included. Home storage may avoid a vault bill but require security and insurance; a bank box charges rent; a private vault may add percentage and fixed fees. Compare incremental annual and exit costs at your holding value.
Can I sell gold directly from a private vault?
Some platforms offer buyback without personal transport, while others require withdrawal or a third-party dealer. Request the expected net proceeds, commission, settlement route and timing. Compare an outside dealer where practical rather than assuming the integrated option is the best price.
Internal links and exact ranking actions
| Link from / to | Anchor and placement instruction |
|---|---|
| Article 3: Ownership terms | Use ‘allocated, segregated and unallocated storage’ in the private-vault section. |
| Article 4: Gold storage fees | Link ‘calculate the true annual storage cost’ beside the cost section. |
| Article 6: Safe gold buying | Use ‘safe physical-gold buying checklist’ after the decision framework. |
| Article 8: Selling stored gold | Link ‘sell or withdraw vaulted gold’ after the buyback FAQ. |
| Article 1: GoldBroker review | Use ‘review GoldBroker’s storage and fees’ as an example only after the neutral framework. |
| Gold & Silver hub | Place under ‘Choose storage’ and link from all buying guides. |
- Create a printable storage comparison worksheet with blank insurance, access and annual-cost fields.
- Obtain current rental or insurance wording for any named bank example; do not generalise one bank’s terms to all banks.
- Link from the safe-buying guide, ownership glossary, cost calculator and provider reviews.
- Publish the five-document evidence table as a citeable checklist for consumer-finance outreach.
- Create a short email lesson around the difference between physical security and insurance cover.
- Monitor queries for insurance, access, home safes and bank boxes; update with official documents rather than forum claims.
- Have a qualified reviewer check insurance wording annually; avoid universal FSCS coverage statements.
- Measure calculator and checklist completions before adding any provider CTA.
Sources to cite and recheck
General information, not personal financial advice. Crypto Financial Care is an independent publication and is not authorised or regulated by the Financial Conduct Authority. Reviewed by the Crypto Financial Care editorial team. Last updated 30 October 2026.